Fuel costs are driving inflation up. Is it time to swap to a cheaper-to-run car?
UK inflation hit 3.5% in September, driven by fuel. Here's how to cut your running costs, and when swapping to a hybrid or EV makes sense.
Read more
If you've ever thought about changing your car, refinancing, or clearing your finance early, you've probably come across the term "settlement figure." It sounds like it should be simple, and in some ways it is, but it rarely matches the number drivers expect.
A settlement figure is the amount you'd need to pay to clear your finance agreement in full, on a specific date. Drivers usually request one when they're selling, trading in, refinancing, or just curious where they stand. And it's worth knowing upfront: your settlement figure is almost never the same as your remaining balance.
Here, we'll walk through how it's calculated, how to request one, and how it fits into the bigger decision of whether now's the time to change your car.
Thinking about changing your car? Find out how your settlement figure compares to your vehicle's value with swoppa. Click here to learn more.
A settlement figure is the total amount required to pay off your finance agreement in full, on a specific date. It applies across most car finance types, including PCP, Hire Purchase and personal loans used to buy a car.
It's not simply what's left on your monthly statement. It's a precise figure, calculated for a particular day, that clears everything you owe under the agreement.
These two numbers are easy to mix up, but they're not the same thing.
Your outstanding balance is roughly what's left if you added up your remaining monthly payments. Your settlement figure is the actual amount needed to clear the agreement today, and it can be higher or lower than that rough total. That's because settlement figures often factor in:
You'll typically need a settlement figure in a handful of situations:
In each case, the settlement figure is the starting point for working out what you actually walk away with.
A settlement figure isn't just your remaining capital. It's usually made up of:
At its simplest, the calculation looks like this:
Remaining Finance
+ Interest Payable
− Interest Rebate (where applicable)
+ Fees
= Settlement Figure
| Outstanding finance | £12,800 |
|---|---|
| Interest adjustment | £120 |
| Admin fee | £25 |
| Settlement figure | £12,945 |
This catches a lot of drivers off guard, and it usually comes down to one or more of these:
None of this means you're being overcharged. It just means the figure reflects more than your remaining payments added up.
There are a few straightforward ways to request one:
Most requests ask for the same basics:
Settlement figures are usually valid for 7 to 28 days, depending on the lender. They expire because your balance changes daily as interest accrues, so a figure from a month ago won't be accurate today. If yours has expired, requesting a new one takes the same few minutes as the first time.
No. Requesting a settlement figure is simply a quotation, not a commitment. There's no obligation to act on it, and you can request one just to check where you stand without any pressure to settle straight away.
Yes, in most cases. Settling early can reduce the total interest you pay overall, though some agreements include an early settlement charge that offsets part of the saving. Under the Consumer Credit Act, UK drivers have a legal right to settle finance agreements early, and lenders are required to provide a settlement figure on request.
It's worth weighing the numbers before deciding. Clearing finance early can free you from monthly payments sooner, but if there's a charge attached, it's worth checking whether the saving still works in your favour.
It depends on your situation, but a few scenarios make it worth considering:
These two numbers get confused constantly, but they answer different questions.
| Settlement Figure | Car Value | |
|---|---|---|
| What it is | Amount owed | Current market value |
| Where it comes from | From your lender | Based on the market |
| How often it changes | Changes daily | Changes with market conditions |
| What it's used for | Clearing your finance | Selling or trading in |
Neither number alone tells you whether changing your car makes sense. It's the gap between them, your equity, that actually answers that.
Knowing your settlement figure is useful, but on its own it can't answer the questions that actually matter:
To answer those, you need your settlement figure alongside your car's current value, your equity position, and a realistic look at affordability. Your settlement figure is one piece of that picture, not the whole thing.
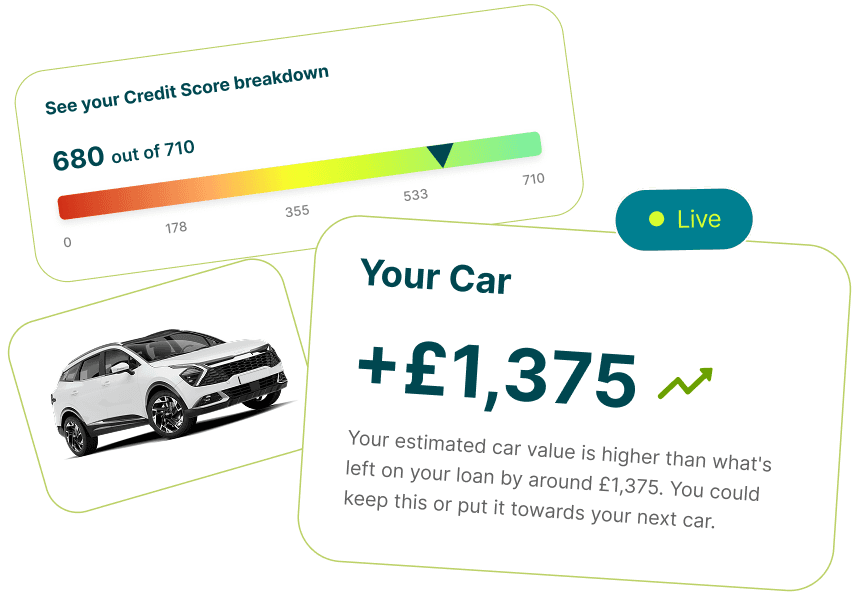
Rather than just telling you what you owe, swoppa brings the full picture together:
Discover your swoppa Score and see whether now is the right time to change your car.
A settlement figure is the total amount needed to pay off your car finance agreement in full, on a specific date.
It's the exact figure required to clear your car finance, typically requested when selling, refinancing, trading in or upgrading.
It's your remaining finance, plus outstanding interest, minus any interest rebate, plus fees where applicable.
Because it includes interest owed up to the settlement date and, in some cases, fees or early settlement adjustments that don't show up in your remaining balance.
Request it through your lender's portal, app, phone line, online account, or via a dealership if you're arranging a trade-in.
Usually between 7 and 28 days, depending on your lender, since your balance changes daily as interest accrues.
Yes. It's a quotation only, with no obligation to act on it.
Yes, in most cases, and UK drivers have a legal right to do so under the Consumer Credit Act, though some agreements include an early settlement adjustment.
No. Your outstanding balance is a rough total of what's left, while your settlement figure is the precise amount needed to clear the agreement, which can include interest, fees or rebates.
Yes, since interest accrues daily, which is also why settlement figures only stay valid for a limited window.
Ready to see where you stand? Check your car's value and discover your swoppa Score today. Click here to learn more.
Additional Resources
Track what your car’s worth, what you owe, and when it’s the right time to change - all in one simple score.
UK inflation hit 3.5% in September, driven by fuel. Here's how to cut your running costs, and when swapping to a hybrid or EV makes sense.
Read more
Most drivers held off changing car until after the Budget. Here's what it changed for motorists and how to decide whether to move now or wait.
Read more
Waiting on a car finance commission complaint? Here's what selling, settling or swapping your car does — and doesn't — change, plus what paperwork to keep.
Read moreUK inflation hit 3.5% in September, driven by fuel. Here's how to cut your running costs, and when swapping to a hybrid or EV makes sense.
Read moreMost drivers held off changing car until after the Budget. Here's what it changed for motorists and how to decide whether to move now or wait.
Read moreWaiting on a car finance commission complaint? Here's what selling, settling or swapping your car does — and doesn't — change, plus what paperwork to keep.
Read more
TAL Marketing Group Limited trading as swoppa is registered in England and Wales under company number: 10612899. Registered Office Address: Work Life, Brown Street, Manchester, England, M2 1DH.
TAL Marketing Group Limited t/a swoppa is an appointed representative of Creative Finance Corp LTD under reference FRN 968428. Creative Finance Corp LTD is authorised and regulated by the Financial Conduct Authority under reference FRN 702435, and is the principal firm of TAL Marketing Group Limited. We act as a credit broker not a lender. We work with a number of carefully selected credit providers who may be able to offer you finance for your purchase. (Written Quotation available upon request.) Whichever lender we introduce you to, we will typically receive commission from them (either a fixed fee or a fixed percentage of the amount you borrow) and this may or may not affect the total amount repayable. The lender will disclose this information before you enter into an agreement which only occurs with your express consent. The lenders we work with could pay commission at different rates and you will be notified of the amount we are paid before completion. All finance is subject to status and income. Terms and conditions apply. Applicants must be 18 years or over. We are only able to offer finance products from these providers. As we are a credit broker and have a commercial relationship with the lender, the introduction we make is not impartial, but we will make introductions in line with your needs, subject to your circumstances.
TAL Marketing Group Limited t/a swoppa are registered with the Information Commissioner's Office under registration number ZB241343.Your details will be shared with 3rd parties, where it is necessary for our legitimate interests (or those of a third party) and your interests, and your fundamental rights do not override those interests, such as companies that can improve your current financial circumstances